
Paying off debt on a low income can feel overwhelming, especially when most of your money goes toward rent, groceries, transportation, utilities, and other essential expenses. After paying your bills, you may have very little left to reduce your debt. However, with a realistic budget, a clear repayment strategy, and consistent effort, you can gradually reduce what you owe and work toward financial stability.
The key is not necessarily to make large payments immediately. Instead, focus on managing your money carefully, avoiding additional debt, and putting whatever amount you can afford toward your balances.
In this guide, you will learn how to pay off debt faster on a low income, choose the right repayment method, reduce expenses, increase your available income, and avoid common mistakes that can slow down your progress.
1. Understand Exactly How Much Debt You Owe
Before creating a repayment plan, you need a clear picture of your financial situation. If you have multiple credit cards, personal loans, medical bills, or other outstanding balances, list them in one place.
For each debt, write down:
- The total amount you owe.
- The interest rate.
- The minimum monthly payment.
- The payment due date.
- Any late fees or additional charges.
- Whether the interest rate is fixed or variable.
This information helps you understand which debts are costing you the most and which payments need immediate attention.
Create a Simple Debt List
For example, your debt list might look like this:
| Debt Type | Outstanding Balance | Interest Rate | Minimum Monthly Payment |
|---|---|---|---|
| Credit card | $1,200 | 24% | $50 |
| Personal loan | $2,500 | 14% | $100 |
| Medical bill | $600 | 0% | $50 |
| Total | $4,300 | — | $200 |
These figures are illustrative. Your actual balances, interest rates, and payment requirements may be different.
Once you have listed everything, calculate your total debt and minimum monthly payments. This gives you a starting point for building a repayment strategy that fits your income.
2. Create a Budget Based on Your Actual Income
A realistic budget is one of the most useful tools for paying off debt on a low income. It shows where your money goes and helps you identify an amount you can consistently put toward repayment.
Start with your monthly take-home income, which is the money you receive after taxes and other payroll deductions.
Next, subtract essential expenses such as:
- Rent or housing payments.
- Groceries and basic household supplies.
- Electricity, water, gas, and other utilities.
- Transportation to work.
- Essential medical costs.
- Childcare and necessary family expenses.
- Required debt minimum payments.
The remaining amount is what you can potentially use for extra debt payments, savings, and other necessary spending.
Example of a Monthly Budget
Suppose your take-home income is $2,000 per month.
| Category | Monthly Amount |
|---|---|
| Housing | $650 |
| Groceries | $300 |
| Utilities | $150 |
| Transportation | $150 |
| Phone and internet | $60 |
| Medical and personal essentials | $90 |
| Minimum debt payments | $200 |
| Total expenses | $1,600 |
| Money remaining | $400 |
In this example, $400 remains after the listed expenses. You might use part of it for additional debt payments, a small emergency fund, and irregular expenses that do not appear in every monthly budget.
Do not assume that the entire remaining amount is available for debt repayment. Include overlooked costs such as clothing, annual bills, school expenses, and unexpected repairs before deciding how much you can safely commit.
3. Choose a Debt Repayment Method
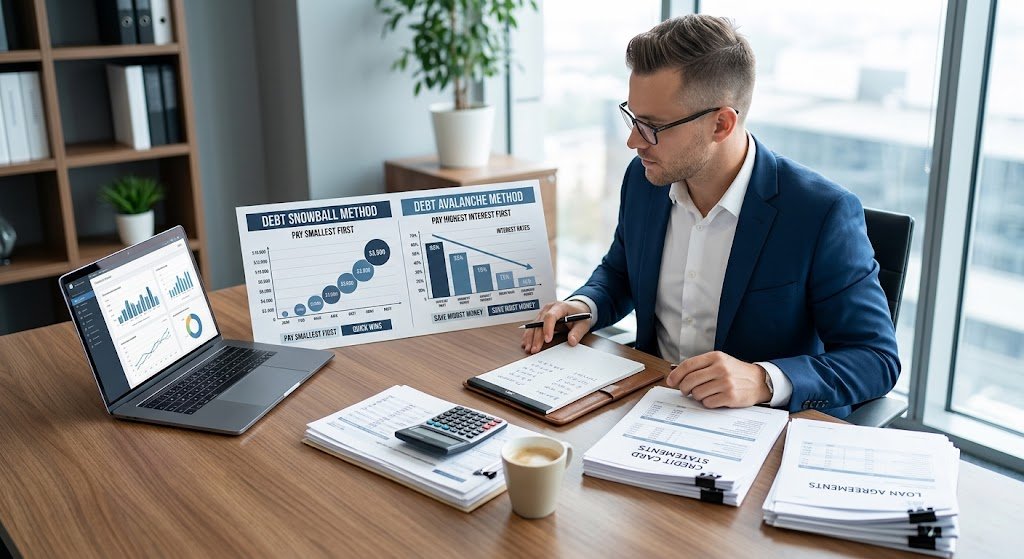
There are two common approaches to paying off multiple debts: the debt avalanche method and the debt snowball method. Both can work on a low income, but they focus on different priorities.
The Debt Avalanche Method
With the debt avalanche method, you make the required minimum payments on all debts and put extra money toward the debt with the highest interest rate.
After that debt is paid off, you redirect the money you were paying toward the next-highest-interest debt.
Why it can help: Paying down expensive debt first can reduce the total interest you pay, assuming other terms and fees are comparable.
For example, if your credit card charges 24% interest and your personal loan charges 14%, you would generally prioritize extra payments toward the credit card while keeping up with the required payments on the personal loan.
This method is especially useful when minimizing interest costs is your main priority.
The Debt Snowball Method
With the debt snowball method, you focus extra payments on your smallest debt balance first, regardless of the interest rate.
You continue making required minimum payments on your other debts. Once the smallest balance is paid off, you apply the money you were using for that debt to the next-smallest balance.
Why it can help: Paying off a small balance can give you a sense of progress and make it easier to stay motivated.
For example, if you owe $200 on one bill, $800 on another, and $2,000 on a third, you would focus on the $200 balance first.
The snowball method may cost more in interest than the avalanche method, particularly if a larger debt has a much higher rate.
Which Method Should You Choose?
| Feature | Debt Avalanche | Debt Snowball |
|---|---|---|
| First priority | Highest interest rate | Smallest balance |
| Main benefit | Usually minimizes interest | Provides early wins |
| Best suited for | People focused on reducing borrowing costs | People motivated by visible progress |
| Main drawback | First payoff may take longer | May cost more interest |
Choose the approach you are most likely to follow consistently. If one debt has a very high interest rate or serious consequences for missed payments, consider those factors before following either method strictly.
4. Pay More Than the Minimum When Possible
Minimum payments can help keep an account current, but they may not reduce the principal quickly, particularly when interest rates are high.
If you can afford to pay more than the minimum without neglecting essential expenses, direct the extra amount toward your chosen target debt.
For example, suppose your minimum credit card payment is $40. If your budget allows you to pay $70, the additional $30 can help reduce the balance faster, subject to how your lender applies payments and calculates interest.
Even a small additional payment can make a difference when repeated over time.
However, avoid setting an unrealistic payment amount that forces you to borrow again before the month ends. A sustainable payment is more useful than an ambitious plan you cannot maintain.
5. Reduce Expenses Without Sacrificing Essentials
When your income is limited, cutting expenses may create some extra money for debt repayment. The goal is to identify spending you can reduce without compromising your health, safety, or ability to work.
Review Your Monthly Subscriptions
Look through your bank statements and identify recurring charges for services you rarely use.
You may be able to cancel unused streaming services, paid apps, memberships, or other optional subscriptions.
Even a few small reductions can create extra room in your budget.
Plan Meals and Grocery Shopping
Food is an essential expense, but planning can help prevent waste and unnecessary purchases.
Try these practical steps:
- Prepare a weekly meal plan.
- Create a shopping list before visiting the store.
- Compare unit prices and choose affordable alternatives.
- Cook meals at home when practical.
- Use leftovers safely.
- Avoid buying groceries when you are hungry if that leads to extra spending.
You do not need to eliminate foods you enjoy. Focus on making your usual spending more efficient.
Review Phone, Internet, and Utility Costs
Check whether a less expensive phone or internet plan would meet your needs. Compare providers when available, and reduce energy use where practical.
Before changing a service, consider cancellation fees, coverage, reliability, and whether the change could affect your work.
Limit Impulse Purchases
Before making a nonessential purchase, wait a day or two and ask whether it fits your budget.
You can also set a small personal spending allowance instead of trying to eliminate every enjoyable purchase. A realistic budget is often easier to maintain over the long term.
6. Find Ways to Increase Your Income
Reducing expenses has limits. If most of your income already goes toward essential bills, earning additional money may be the most practical way to accelerate debt repayment.
You do not necessarily need a second full-time job. Start by considering opportunities that fit your schedule, skills, location, and responsibilities.
Consider Freelance Work
If you have useful skills, you might offer services such as writing, graphic design, translation, video editing, bookkeeping, or website support.
Start with services you can deliver reliably and avoid paying large upfront fees for promises of guaranteed work.
Sell Unused Items
You may have clothing, electronics, furniture, or household items you no longer need. Selling these items can generate a one-time payment that you can put toward a debt.
Do not sell essential items you need for work, education, health, or daily living simply to make a repayment.
Look for Part-Time or Flexible Work
Depending on what is available locally, you might consider weekend work, tutoring, delivery services, temporary shifts, or other flexible opportunities.
Calculate the actual amount you would keep after transportation, supplies, taxes, and other work-related expenses.
Use Extra Income Strategically
If you receive overtime pay, a bonus, a refund, or money from a side job, decide in advance how to use it.
After accounting for essential expenses and any urgent financial needs, you can put an appropriate portion toward your target debt.
Extra income is most helpful when it reduces your balance rather than becoming a reason to increase spending.
7. Contact Your Creditors if Payments Are Difficult
If you are struggling to make your required payments, contact your lender or creditor before the situation gets worse.
Explain your circumstances and ask whether any options are available. Depending on the creditor and your location, these might include:
- A temporary payment arrangement.
- A lower interest rate.
- A revised repayment schedule.
- A hardship program.
- Waiver or reduction of certain fees.
- A payment plan for overdue bills.
Not every creditor offers these options, and some arrangements may affect your credit history or increase the total amount you repay. Ask for the terms in writing and understand the consequences before agreeing.
If you cannot afford all your bills, prioritize essential needs such as housing, utilities, food, and transportation needed for work. Certain debts can also have serious consequences if unpaid, so consider the legal and practical risks associated with each obligation.
A reputable nonprofit credit counselor or local debt-advice service may be able to help you understand your options.
8. Avoid Taking on More Debt
It is difficult to make progress when new borrowing keeps replacing the debt you have already paid down.
While paying off existing balances, try to avoid unnecessary credit card purchases, payday loans, and other expensive borrowing.
Build a Small Emergency Cushion
An unexpected expense can force you to borrow again if you have no money available. A modest emergency fund can help cover urgent costs while you continue working toward debt freedom.
You do not have to wait until you have a large emergency fund before making extra debt payments. If you are already behind on bills or dealing with high-interest debt, balance your repayment plan with the need for a small cash reserve.
The right amount depends on your circumstances. Start with a manageable target, such as enough to cover one common unexpected expense, and build it gradually.
Use Credit Carefully
If you keep a credit card open, avoid treating the available credit limit as money you can spend. Make new purchases only when you have a realistic plan to pay for them.
If using a card makes it harder to control spending, consider keeping it out of easy reach while you focus on repayment.
9. Be Careful With Debt Consolidation
Debt consolidation combines multiple debts into one new loan or repayment arrangement. Depending on the terms, it may simplify payments or lower your interest costs.
However, consolidation is not automatically a good choice for someone on a low income.
Before accepting an offer, compare:
- The new interest rate.
- Origination and other fees.
- The repayment period.
- The total amount you will pay.
- Whether the rate can change.
- Whether the monthly payment is affordable.
- What happens if you miss a payment.
A lower monthly payment may result from extending the repayment period, which can increase the total interest you pay.
Be cautious of companies that guarantee they can erase your debt, demand large upfront fees, or instruct you to stop communicating with your creditors without clearly explaining the risks.
You do not need to take out another loan to use the avalanche or snowball method.
10. Make a Debt Repayment Plan You Can Follow
A debt repayment plan turns a general intention into specific monthly actions.
Follow these steps to create yours.
Step 1: Calculate Your Take-Home Income
Write down the income you can reasonably expect each month. If your earnings change, use a conservative estimate based on your typical income and plan around essential expenses first.
Step 2: List Essential Expenses
Include housing, food, utilities, transportation, medical needs, and other unavoidable costs.
Make sure you account for irregular expenses by setting aside money each month when possible.
Step 3: Add Up Required Debt Payments
Calculate the minimum payments and due dates for all debts. If you cannot afford the required payments, contact the creditors to discuss possible arrangements.
Step 4: Choose a Target Debt
Use the avalanche method to prioritize high-interest debt or the snowball method to prioritize small balances.
Make sure you also consider overdue accounts and debts with serious consequences if unpaid.
Step 5: Decide on an Affordable Extra Payment
Choose an amount you can sustain after covering essentials and accounting for irregular expenses.
If you can only afford a small extra payment, start there. You can increase it later if your financial situation improves.
Step 6: Review Your Progress Monthly
Track each balance and confirm that payments have been processed correctly. When a debt is paid off, redirect the money you were paying toward the next target.
Celebrate meaningful progress without spending money you need for bills or repayment.
Example: Paying Off Debt on a Low Income
Imagine you earn $1,800 per month after deductions and have the following debts:
| Debt | Balance | Minimum Payment |
|---|---|---|
| Credit card | $900 | $45 |
| Personal loan | $1,800 | $90 |
| Medical bill | $300 | $25 |
| Total | $3,000 | $160 |
Suppose your essential living expenses, excluding debt payments, total $1,400. After the $160 in minimum payments, you have $240 remaining.
You might decide to allocate $140 to additional debt repayment and keep $100 for irregular expenses and a small emergency cushion. Your total monthly debt payments would then be $300, assuming the minimum payments remain unchanged.
If you use the avalanche method, the extra $140 would go toward whichever debt has the highest interest rate. If you use the snowball method, it would go toward the $300 medical bill first, provided that doing so does not overlook more urgent obligations.
The exact payoff date will depend on interest rates, fees, payment timing, and how your creditors apply payments. The important point is that a clear plan helps you direct your money intentionally.
Common Mistakes to Avoid When Paying Off Debt
Even with a repayment plan, certain mistakes can make progress more difficult.
Ignoring Essential Expenses
Do not put every available dollar toward debt if it leaves you unable to pay for food, housing, medication, or transportation to work.
Missing Minimum Payments Without Contacting the Lender
Missed payments can lead to fees, additional interest, collection activity, or other consequences. If you cannot make a payment, contact the creditor as soon as possible and ask about your options.
Trying to Pay Everything Off Too Quickly
An unrealistic repayment plan can leave you short of cash and push you toward more borrowing. Choose an amount that fits your actual budget.
Using New Loans Without Comparing Costs
A new loan may appear to simplify your finances, but fees and longer repayment periods can make it more expensive. Compare the full cost before making a decision.
Giving Up After a Difficult Month
Your income or expenses may change unexpectedly. If you miss a savings or extra-payment target, review your budget and restart when possible rather than abandoning the entire plan.
Frequently Asked Questions
1. What is the fastest way to pay off debt on a low income?
Start by listing your debts, covering essential expenses, and making required payments where possible. Then direct extra money toward either the highest-interest debt or the smallest balance. Reducing avoidable expenses and increasing income can also speed up repayment.
2. Should I pay off debt or save money first?
The answer depends on your circumstances. Maintaining essential expenses and required debt payments is important, while a small emergency cushion can prevent additional borrowing. After that, high-interest debt may deserve priority because it can grow quickly.
3. Is it better to pay off the smallest debt first?
The snowball method can provide motivation by helping you eliminate small balances quickly. However, the avalanche method usually reduces interest costs when you prioritize the highest-interest debt. Choose the method that best fits your financial priorities and helps you stay consistent.
4. Can I pay off debt without increasing my income?
Yes. You may be able to make progress by creating a realistic budget, reducing optional spending, and directing extra money toward your balances. However, if your essential expenses already consume your entire income, finding additional income or negotiating more manageable payments may be necessary.
5. What should I do if I cannot afford my minimum payments?
Contact your creditors promptly and explain your financial situation. Ask about hardship programs, revised payment plans, or other available arrangements. If necessary, seek help from a reputable credit counselor or local debt-advice service.
6. Should I use my emergency savings to pay off debt?
It depends on the urgency of your debt and how much cash you have available. Using every dollar of savings may leave you vulnerable to an unexpected expense and force you to borrow again. Consider keeping a modest emergency reserve while prioritizing expensive debt.
7. How much extra should I pay toward debt each month?
Pay an amount you can afford after covering essential living costs, required payments, and foreseeable expenses. Even a small additional payment can help. Increase it gradually when your budget allows.
8. How long does it take to become debt-free?
The timeline depends on your total balance, interest rates, fees, and monthly payments. A debt repayment calculator can help estimate your payoff date. Review your progress regularly and update the estimate as your balances change.
Conclusion
Paying off debt faster on a low income is challenging, but you can make progress with a practical strategy. Start by understanding your total debt, creating a realistic budget, and choosing a repayment method that suits your needs.
Look for reasonable ways to reduce expenses, explore opportunities to increase your income, and contact creditors if you are struggling with payments. At the same time, protect your ability to cover essential needs and maintain a small emergency cushion when possible.
You do not need to solve every financial problem at once. Focus on the next manageable step, make consistent payments, and adjust your plan when circumstances change. Over time, these habits can help you reduce debt, regain control of your finances, and build a more stable financial future.
Financial disclaimer: This article is for educational and informational purposes only and does not constitute personalized financial, legal, tax, or credit advice. Debt repayment options, creditor rights, consumer protections, and credit-reporting rules vary by country and provider. Review your loan agreements and consider seeking qualified financial or debt advice for your circumstances.

Leave a Reply