
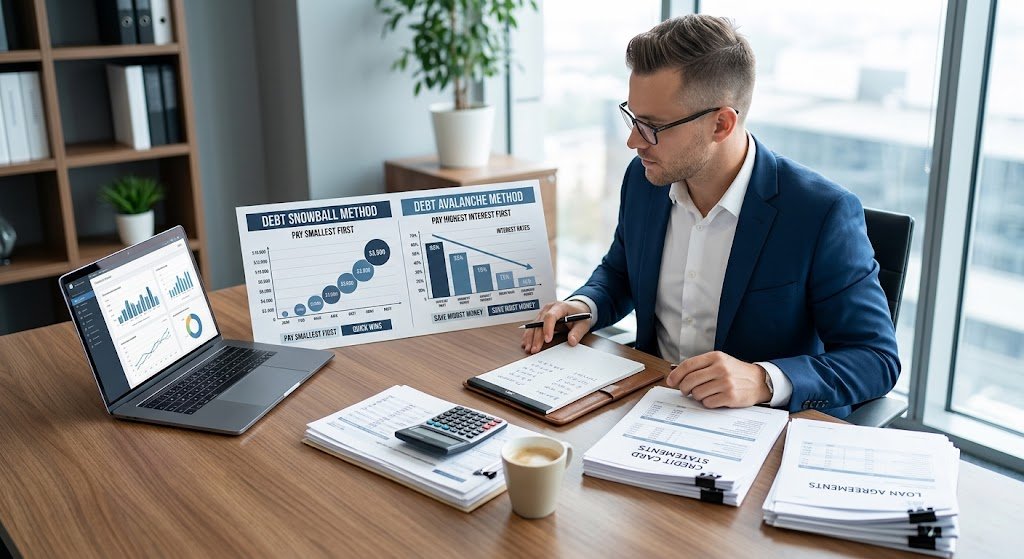
Paying off debt can be challenging, especially when you have multiple credit cards, personal loans, or other outstanding balances. You may know that you want to become debt-free, but deciding which debt to pay first can make a significant difference in your progress.
Two popular debt repayment strategies are the debt snowball method and the debt avalanche method. Both approaches help you organize your payments, reduce outstanding balances, and work toward becoming debt-free. However, they use different strategies to determine which debt receives your extra money first.
The debt snowball method focuses on paying off the smallest balance first, while the debt avalanche method prioritizes the debt with the highest interest rate. One can provide quicker psychological wins, while the other can help reduce total interest costs.
In this guide, you will learn how both methods work, compare their advantages and disadvantages, explore practical examples, and discover how to choose the best debt repayment strategy for your financial situation.
What Is the Debt Snowball Method?
The debt snowball method is a debt repayment strategy that focuses on eliminating your smallest debt balance first, regardless of the interest rate.
You continue making the required minimum payments on all your other debts. Any extra money you can afford goes toward the debt with the smallest outstanding balance.
Once that debt is paid off, you take the money you were using for its payment and add it to the payment for your next-smallest debt. As you eliminate more balances, your payments toward the remaining debts become larger, creating a snowball effect.
How the Debt Snowball Method Works
Follow these steps to use the debt snowball method:
- List all your debts, including their balances, interest rates, and minimum payments.
- Arrange the debts from the smallest balance to the largest balance.
- Make the required minimum payments on every debt, where possible.
- Put any extra money toward the smallest debt.
- Continue until the smallest debt is completely paid off.
- Redirect the payment you were making toward that debt to the next-smallest balance.
- Repeat the process until all your debts are paid off.
The main idea is to build momentum by eliminating individual debts one at a time.
Example of the Debt Snowball Method
Suppose you have three debts:
| Debt | Outstanding Balance | Interest Rate | Minimum Payment |
|---|---|---|---|
| Medical bill | $300 | 0% | $30 |
| Credit card | $900 | 22% | $45 |
| Personal loan | $2,000 | 12% | $80 |
| Total | $3,200 | — | $155 |
With the debt snowball method, you would prioritize the $300 medical bill first.
You would continue paying the minimum required amounts on the credit card and personal loan while putting extra money toward the medical bill.
After paying off the medical bill, you would redirect the money previously used for that payment toward the $900 credit card. Once the credit card is paid off, you would focus on the personal loan.
Your exact payoff dates would depend on your available monthly payment, interest calculations, fees, and the terms of each debt.
Advantages of the Debt Snowball Method
1. Provides quick wins
Paying off a small balance can give you a sense of achievement. This can be particularly helpful if you feel overwhelmed by the number of debts you have.
2. Makes progress easier to see
Watching individual balances disappear can help you recognize your progress even when your total debt is still substantial.
3. Simplifies your finances
Every time you eliminate a debt, you have one fewer payment and account balance to manage.
4. Helps build consistent habits
For people who struggle with motivation, seeing results early may make it easier to continue following a repayment plan.
Disadvantages of the Debt Snowball Method
1. You may pay more interest
Because the smallest balance receives priority, a larger debt with a high interest rate may remain unpaid for longer.
2. The first debt paid off may not be the most expensive
A small debt with a low interest rate could receive extra payments before a much larger debt charging a higher rate.
3. It does not always produce the lowest total cost
If interest rates differ significantly, prioritizing balances rather than interest rates can increase the amount of interest you pay over time.
The snowball method can still be useful if its motivational benefits help you stay consistent when another strategy might feel difficult to maintain.
What Is the Debt Avalanche Method?
The debt avalanche method is a debt repayment strategy that prioritizes the debt with the highest interest rate.
Instead of starting with the smallest balance, you arrange your debts according to their interest rates, from highest to lowest. You make the required minimum payments on all debts and direct your extra money toward the debt charging the highest interest rate.
After that debt is paid off, you move to the debt with the next-highest interest rate.
This approach targets the debts that generally cost you the most to carry.
How the Debt Avalanche Method Works
Follow these steps to use the debt avalanche method:
- List all your debts, including balances, interest rates, and minimum payments.
- Arrange them from the highest interest rate to the lowest interest rate.
- Continue making the required minimum payments on every debt, where possible.
- Put any extra money toward the debt with the highest interest rate.
- Continue until that debt is completely paid off.
- Redirect the payment you were making toward that debt to the next-highest-interest debt.
- Repeat the process until all your debts are paid off.
If two debts have the same interest rate, you can prioritize the smaller balance between them or consider other relevant factors, such as fees and repayment terms.
Example of the Debt Avalanche Method
Using the same debts from the previous example, the repayment order changes:
| Debt | Outstanding Balance | Interest Rate | Repayment Priority |
|---|---|---|---|
| Credit card | $900 | 22% | First |
| Personal loan | $2,000 | 12% | Second |
| Medical bill | $300 | 0% | Third |
| Total | $3,200 | — | — |
With the debt avalanche method, you would prioritize the credit card because it has the highest interest rate.
You would keep making the required payments on the personal loan and medical bill while putting extra money toward the credit card.
After paying off the credit card, you would direct your extra payments toward the personal loan. The medical bill would receive priority afterward, assuming its terms remain unchanged and there are no special deadlines or consequences that require earlier action.
Advantages of the Debt Avalanche Method
1. Can reduce total interest costs
By prioritizing the highest-interest debt, you generally reduce the amount of interest that accumulates compared with paying the same total amount toward lower-interest debts first.
2. Can help you become debt-free more efficiently
When interest rates vary significantly, targeting the most expensive debt can make your repayment money work harder.
3. Addresses expensive borrowing first
Credit cards and other high-interest loans can become costly if balances remain outstanding. The avalanche method directs your extra payments toward these debts.
4. Encourages cost-focused financial decisions
This approach is useful for people who prefer to compare the financial cost of different repayment choices rather than prioritize quick wins.
Disadvantages of the Debt Avalanche Method
1. Your first payoff may take longer
If your highest-interest debt has a large balance, it may take months or years to eliminate it. This can make progress feel slower.
2. You may need more patience
People who are motivated by seeing individual accounts paid off may find it difficult to continue when the first target takes a long time.
3. It requires accurate information
You need to know your interest rates, minimum payments, and any fees or promotional terms to rank your debts effectively.Despite these disadvantages, the avalanche method is often a strong choice when reducing interest costs is your main goal.
Debt Snowball vs. Debt Avalanche: Key Differences
Both strategies involve paying the required minimums on your debts and concentrating extra payments on one balance at a time. Their main difference is which balance receives priority.
| Feature | Debt Snowball | Debt Avalanche |
|---|---|---|
| Main priority | Smallest balance | Highest interest rate |
| First goal | Eliminate a small debt | Reduce expensive debt |
| Main advantage | Quick psychological wins | Usually lower interest costs |
| Motivation | Visible progress | Financial savings |
| First payoff | May happen sooner | Depends on the highest-rate balance |
| Total interest | May be higher | Usually lower when other factors are comparable |
| Best suited for | People who need motivation | People focused on minimizing interest |
Neither method is automatically best for every person. Your debt balances, interest rates, monthly budget, and personal preferences all matter.
Which Method Saves More Money?
In many situations, the debt avalanche method saves more money because it prioritizes the balance with the highest interest rate.
Interest is generally calculated based on your outstanding balance, the applicable rate, and the lender’s calculation method. Paying down a high-interest balance sooner can reduce the interest that accumulates while you repay your other debts.
A Simple Interest Example
Imagine you have two debts:
- Credit card balance: $1,000 at 24% annual interest.
- Personal loan balance: $1,000 at 10% annual interest.
For a simplified illustration, assume both balances remain unchanged for a year and use the stated annual rates without fees or compounding.
The credit card would generate approximately $240 in interest, while the personal loan would generate approximately $100.
This is not an exact prediction of what you will pay, because real lenders may calculate interest daily or monthly and your payments will reduce balances. However, the example shows why a debt with a higher interest rate often deserves priority.
If you have extra money available, paying down the credit card first generally reduces interest costs more effectively than paying the personal loan first, assuming comparable payment terms and no special conditions.
The avalanche method’s advantage can be smaller when interest rates are similar. It can also be affected by promotional rates, fees, penalties, or special repayment terms.
Which Method Is Easier to Follow on a Low Income?
If you have a limited income, choosing a strategy you can maintain is especially important.
Your budget may not allow you to make large additional payments every month. You may need to focus on small, steady contributions rather than trying to eliminate your debts quickly.
When the Debt Snowball May Be Better
The snowball method may be a good fit if:
- You have several small debts that could be paid off relatively quickly.
- You feel overwhelmed by having multiple outstanding balances.
- You have struggled to stay consistent with previous repayment plans.
- You want to reduce the number of separate payments you manage.
- Early progress would help you remain motivated.
For example, paying off a small $150 balance could give you confidence to continue working toward a larger debt.
However, always check whether the small debt has special consequences or whether a different debt is costing you significantly more in interest.
When the Debt Avalanche May Be Better
The avalanche method may be a better fit if:
- You have high-interest credit card debt.
- Your interest rates vary substantially.
- You can stay motivated without frequent early payoffs.
- You want to minimize the interest you pay.
- You are comfortable following a longer repayment process when necessary.
For example, if one credit card charges 29% interest and a personal loan charges 9%, directing extra payments toward the credit card can be financially beneficial.
You do not need a high income to use the avalanche method. The key is to choose an affordable extra payment and apply it consistently.
How to Choose the Best Debt Repayment Strategy
Before choosing between the snowball and avalanche methods, review your financial situation carefully.
Step 1: List All Your Debts
Write down each outstanding balance, interest rate, minimum payment, due date, and any special repayment conditions.
This gives you a complete picture of your obligations.
Step 2: Check Your Monthly Budget
Calculate your take-home income and subtract essential expenses, required debt payments, and foreseeable costs.
Do not commit money to debt repayment if doing so would leave you unable to afford food, housing, utilities, medication, or necessary transportation.
Step 3: Decide What Matters Most
Ask yourself whether your main priority is reducing interest costs or gaining motivation through quick wins.
If interest savings are your main concern, the avalanche method may be appropriate. If early progress helps you stay consistent, the snowball method may be easier to maintain.
Step 4: Choose an Affordable Extra Payment
Determine how much extra you can realistically pay each month.
Even a small amount can help. If your budget changes, adjust your payment rather than abandoning the plan entirely.
Step 5: Review Your Progress Regularly
Check your balances each month and make sure your payments are being applied correctly.
If your income increases, you may be able to increase your extra payment. If an unexpected expense occurs, adjust your budget and resume your plan when possible.
Can You Combine the Debt Snowball and Avalanche Methods?
Yes. Some people use a hybrid strategy that combines the motivational benefits of the snowball method with the interest savings of the avalanche method.
For example, you might pay off one very small debt to build momentum and then switch to prioritizing the highest-interest debt.
This approach can be useful if you feel overwhelmed by your debts but still want to limit interest costs.
However, there is a trade-off. Paying a lower-interest debt first may cost more than immediately targeting the highest-interest balance. Before choosing a hybrid approach, compare the possible interest cost with the motivational benefit you expect to gain.
You should also consider whether any account is overdue or has serious consequences if you fail to pay it. These issues may deserve attention before following a standard repayment order.
Common Debt Repayment Mistakes to Avoid
Whichever method you choose, avoiding common mistakes can help you make better progress.
1. Missing Required Minimum Payments
Both strategies depend on keeping up with the required payments on your other debts. Missing payments can lead to fees, additional interest, credit-reporting consequences, or collection activity.
If you cannot afford a required payment, contact the creditor to discuss possible arrangements.
2. Using All Your Savings to Repay Debt
Putting every available dollar toward debt may leave you without money for unexpected expenses. That can force you to borrow again.
Consider maintaining a modest emergency reserve while making progress on expensive debt.
3. Taking on More High-Interest Debt
If you continue adding expensive debt while making repayments, your progress may be limited.
Review your spending and avoid unnecessary borrowing whenever possible.
4. Choosing a Plan You Cannot Maintain
A repayment strategy only works if it fits your real financial circumstances. Do not set an extra payment so high that you cannot cover essential expenses.
Start with a manageable amount and increase it when your budget allows.
5. Ignoring Interest Rates and Fees
A debt’s balance alone does not tell you how expensive it is. Check the interest rate, fees, promotional periods, and other terms before deciding which debt should receive extra payments.
Frequently Asked Questions
1. Is the debt snowball or debt avalanche better?
The debt avalanche method is generally better for minimizing interest costs when other terms are comparable. The debt snowball method may be better for people who need quick wins to stay motivated. The best option is the one that fits your finances and that you can follow consistently.
2. Does the debt snowball method cost more?
It can cost more in interest if you pay off lower-interest debts before higher-interest debts. The difference depends on your balances, interest rates, payment amounts, and repayment timeline.
3. Can I use the debt avalanche method with a low income?
Yes. You can use the avalanche method regardless of income level. Make required payments where possible and direct any affordable extra amount toward the highest-interest debt.
4. Should I pay off a small debt or a high-interest debt first?
If minimizing interest is your priority, the high-interest debt is generally the better target. If eliminating a small balance would help you stay motivated, the snowball method may be worth considering. Check for overdue payments and special terms before deciding.
5. What if I cannot afford to pay more than the minimum?
Start by reviewing your budget and identifying whether any expenses can reasonably be reduced. If there is no money left for extra payments, focus on making required payments where possible, avoiding new debt, and contacting creditors if you are struggling.
You can begin making additional payments when your financial circumstances improve.
6. How much extra should I pay toward my debt?
There is no universal amount. Choose an amount you can afford after covering essential expenses, required payments, and foreseeable costs. Consistent extra payments are more sustainable than setting a target that forces you to borrow again.
7. Does paying off debt improve my credit score?
Paying down credit card balances may improve credit utilization, which can help your credit score in some scoring systems. However, the effect depends on your credit history, the scoring model, and other factors. Paying off a loan does not guarantee an immediate increase in your score.
8. Can I switch from the snowball method to the avalanche method?
Yes. Your repayment strategy can change as your financial situation and motivation change. You can start with the snowball method and later prioritize high-interest debt, or switch to another approach that better fits your goals.
Conclusion
The debt snowball and debt avalanche methods can both help you work toward becoming debt-free, but they serve different priorities.
The debt snowball method focuses on the smallest balance first, helping you build momentum through visible progress. The debt avalanche method focuses on the highest interest rate first, which generally helps reduce the total interest you pay.
If saving money on interest is your main goal, the avalanche method is often the stronger financial choice. If quick wins help you remain consistent, the snowball method may be a better fit.
Start by listing your debts, reviewing your budget, and choosing an affordable monthly payment. Make the required payments on your other debts, direct extra money toward your chosen target, and review your progress regularly.
You do not need to pay off everything immediately. A realistic strategy, consistent payments, and careful financial decisions can help you reduce debt and build a more stable financial future.
Financial disclaimer: This article is for educational and informational purposes only and does not constitute personalized financial, legal, tax, or credit advice. Interest calculations, repayment conditions, credit-reporting rules, and consumer protections vary by lender and country. Review your loan agreements and consider seeking qualified financial advice when appropriate.

Leave a Reply