
Credit cards can be useful for everyday purchases, emergencies, and building a credit history. However, when you carry a balance from month to month, interest charges and fees can make it difficult to pay off what you owe. If you have multiple credit cards or a limited monthly income, managing that debt can feel even more challenging.
The good news is that you can take practical steps to regain control of your credit card debt. By understanding your balances, creating a realistic budget, choosing a repayment strategy, and avoiding unnecessary borrowing, you can reduce your debt and improve your financial habits over time.
In this guide, you will learn how to manage credit card debt effectively, reduce interest costs, make a repayment plan, avoid common mistakes, and work toward becoming debt-free.
What Is Credit Card Debt?
Credit card debt is the money you owe a credit card company when you use your card and do not repay the full amount according to your billing terms.
When you make purchases using a credit card, the issuer provides access to borrowed money up to your credit limit. If you pay your statement balance in full by the due date, you can generally avoid interest on ordinary purchases when your card offers a grace period and you meet its conditions.
However, if you carry a balance, interest may be charged on the unpaid amount. Cash advances and certain other transactions may have different fees and interest rules.
For example, suppose you have a credit card balance of $2,000 and an annual interest rate of 24%. If you make only small payments while continuing to use the card, interest can make repayment slower and more expensive.
Understanding how your card works is the first step toward managing it effectively.
1. Know Exactly How Much Credit Card Debt You Have
Before creating a repayment plan, review every credit card account you use.
Record the current balance, interest rate, minimum payment, due date, and any fees. If you have more than one card, put all the information in a single list.
Include the following details:
- Current outstanding balance.
- Annual percentage rate (APR).
- Required minimum monthly payment.
- Payment due date.
- Credit limit.
- Any overdue amount or late fee.
- Promotional interest rates and their expiration dates.
Example of a Credit Card Debt List
| Credit Card | Outstanding Balance | APR | Minimum Payment |
|---|---|---|---|
| Card A | $1,500 | 24% | $60 |
| Card B | $800 | 18% | $40 |
| Card C | $2,200 | 15% | $75 |
| Total | $4,500 | — | $175 |
These figures are examples only. Your actual interest rates, minimum payments, and account terms may differ.
In this example, you owe $4,500 across three cards, with minimum payments totaling $175 per month.
Knowing your total balance helps you understand your financial situation and determine how much you need to budget for repayment.
2. Stop Adding Unnecessary Credit Card Debt
One of the most important steps in managing credit card debt is to prevent your balance from growing while you are trying to pay it off.
If you continue making new purchases on a card while paying only a small amount toward the balance, your debt may decrease very slowly or continue increasing.
Use Cash or Debit for Everyday Purchases
Consider using cash or a debit card for everyday expenses if this helps you stay within your budget.
Before making a purchase, check whether you have enough money available to cover it without borrowing.
You do not necessarily need to stop using every credit card. However, temporarily limiting new charges on a card with a carried balance can make your repayment plan easier to follow.
Remove Unnecessary Spending Triggers
You can also make it harder to spend impulsively by removing saved card details from shopping websites, turning off promotional shopping notifications, or avoiding purchases you cannot currently afford.
If your card is essential for certain expenses, keep those purchases within a clearly defined budget.
The goal is to stop creating additional debt while reducing your existing balance.
3. Create a Budget for Credit Card Repayment
A budget helps you determine how much money you can afford to put toward your credit cards each month.
Start with your monthly take-home income. Then subtract essential expenses such as:
- Housing and rent.
- Groceries.
- Electricity, water, and other utilities.
- Transportation.
- Insurance and medical expenses.
- Childcare and family responsibilities.
- Other required debt payments.
Include irregular expenses such as annual insurance premiums, car repairs, and school costs. Setting aside money for these expenses can help prevent unexpected bills from going onto your credit card.
Example Monthly Budget
Suppose your monthly take-home income is $2,000.
| Category | Monthly Amount |
|---|---|
| Housing | $650 |
| Groceries | $300 |
| Utilities | $150 |
| Transportation | $150 |
| Phone and internet | $60 |
| Medical and personal essentials | $90 |
| Credit card minimum payments | $175 |
| Irregular expenses reserve | $100 |
| Total planned expenses | $1,675 |
| Money remaining | $325 |
In this example, $325 remains after the listed expenses.
You might use some of that money for additional credit card payments while keeping enough available for unexpected expenses and other financial priorities.
Do not assume that every dollar remaining is automatically available for repayment. Make sure your budget includes all essential costs and a reasonable allowance for expenses that vary from month to month.
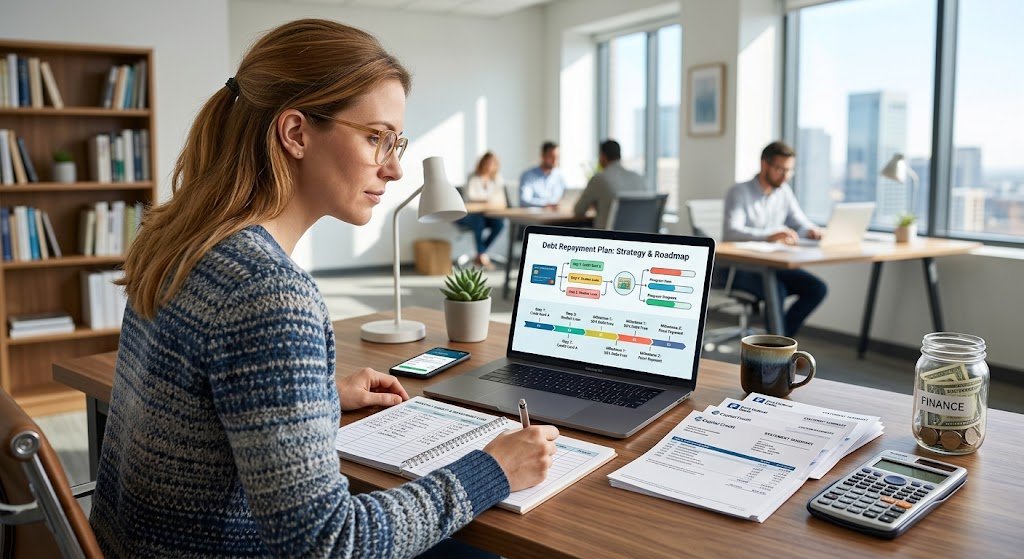
4. Choose the Right Credit Card Repayment Strategy
If you have multiple credit cards, deciding which one to pay first can help you use your money more effectively.
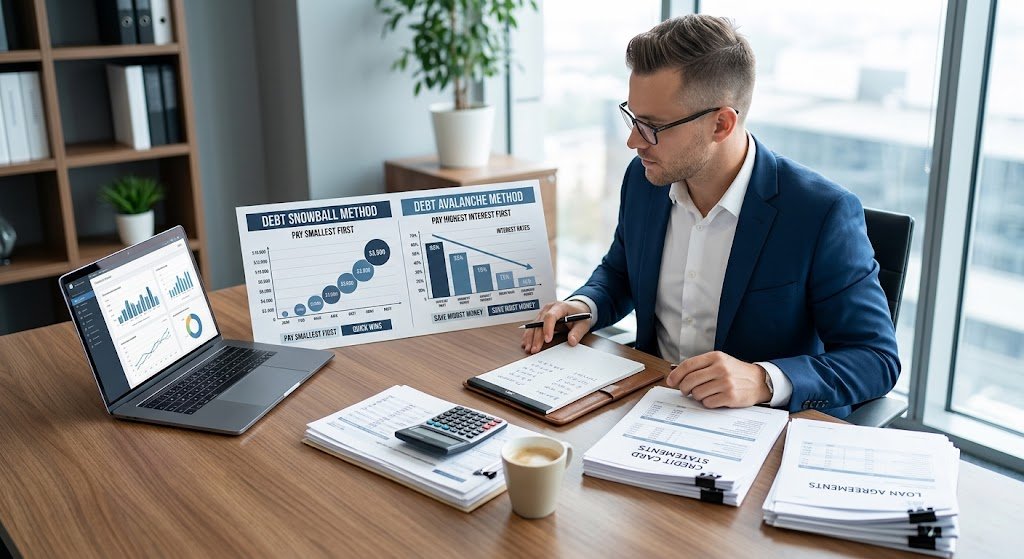
Two popular strategies are the debt avalanche method and the debt snowball method.
Debt Avalanche Method
The debt avalanche method prioritizes the credit card with the highest interest rate.
You make the required minimum payments on all your cards and direct extra money toward the card charging the highest APR. After paying it off, you redirect that payment toward the card with the next-highest rate.
For example, if your cards charge 24%, 18%, and 15% interest, you would generally target the 24% card first.
Main benefit: This method generally reduces total interest costs when other terms are comparable.
Possible drawback: If your highest-interest card has a large balance, it may take longer to pay off your first card completely.
Debt Snowball Method
The debt snowball method prioritizes the card with the smallest balance.
You continue making required minimum payments on the other cards and direct extra money toward the smallest balance. Once that balance is cleared, you focus on the next-smallest one.
For example, if your balances are $300, $800, and $2,000, you would start with the $300 balance, regardless of the interest rates.
Main benefit: Paying off a smaller balance can provide an early sense of achievement and help you stay motivated.
Possible drawback: You may pay more interest if a larger balance has a significantly higher APR.
Which Strategy Should You Use?
| Feature | Debt Avalanche | Debt Snowball |
|---|---|---|
| First priority | Highest interest rate | Smallest balance |
| Main goal | Reduce interest costs | Build repayment momentum |
| Best suited for | People focused on saving money | People motivated by quick wins |
| Potential drawback | First payoff may take longer | May cost more in interest |
Choose the strategy that fits your priorities and that you can maintain consistently. Whichever method you select, continue making the required payments on your other accounts where possible.
5. Pay More Than the Minimum When You Can
Credit card minimum payments are designed to meet the issuer’s repayment requirements, not necessarily to eliminate your balance quickly.
When interest is accumulating, a substantial portion of a small payment may go toward interest and fees rather than reducing the amount you originally borrowed.
If your budget allows, paying more than the minimum can help reduce your balance faster.
Example of Extra Payments
Suppose your credit card balance is $1,000 and the required minimum payment is $40.
If you pay only $40, your balance may decline slowly because interest continues to accrue.
If you can afford to pay $100 instead, the additional $60 can help reduce the balance more quickly, subject to the interest charged and any fees.
The exact repayment time depends on your APR, how the issuer calculates interest, and whether you make new purchases.
Even a modest extra payment can help when you repeat it consistently. However, do not set a payment so high that you cannot afford essential expenses or end up borrowing again.
6. Understand Your Credit Card Interest Rate
Knowing how credit card interest works can help you understand why your debt may be taking longer to repay than expected.
Your annual percentage rate, or APR, is an annualized measure of the cost of borrowing under the applicable terms. Your actual interest charges depend on the card’s agreement, balance, transaction types, payment timing, and interest calculation method.
What Happens When You Carry a Balance?
If you do not pay the full amount required to avoid interest, the issuer may charge interest on the unpaid balance. Depending on the agreement, you may also lose the grace period on new purchases until certain conditions are met.
For example, a card with a high APR can become expensive if you carry a large balance for many months.
To understand your costs:
- Check the APR listed on your statement.
- Review how interest is calculated.
- Check whether different rates apply to purchases, balance transfers, and cash advances.
- Review any promotional rates and their expiration dates.
- Look for fees that could increase your balance.
Cash advances often have separate fees and may begin accruing interest immediately. Check your card agreement before using this feature.
7. Contact Your Credit Card Company for Help
If you are struggling to make payments, contact your credit card issuer before the situation becomes more difficult.
Explain your circumstances and ask whether the issuer offers any options for customers experiencing financial hardship.
Depending on the provider and your location, possible options may include:
- A temporary reduced interest rate.
- A hardship repayment plan.
- A revised payment schedule.
- A temporary payment arrangement.
- A fee waiver or reduction.
- Information about nonprofit credit counseling.
These options are not guaranteed. Ask about eligibility requirements and whether an arrangement could affect your account, credit history, fees, or repayment period.
Get any new terms in writing before agreeing.
If you cannot afford the minimum payments, do not simply ignore the accounts. Contacting the issuer early may give you more options than waiting until payments become seriously overdue.
8. Consider a Balance Transfer Carefully
A balance transfer allows you to move debt from one credit card to another, often with the goal of obtaining a lower interest rate.
Some cards offer promotional APRs on transferred balances for a limited period. This may help reduce interest costs if you can repay a meaningful portion of the balance before the promotional period ends.
However, a balance transfer is not automatically beneficial.
Check These Details Before Transferring a Balance
- The balance transfer fee.
- The promotional interest rate.
- The length of the promotional period.
- The regular APR after the promotion ends.
- Whether new purchases have a different interest rate.
- The amount you can transfer.
- Any conditions for maintaining the promotional rate.
For example, a card may offer a low promotional APR but charge a transfer fee. If the fee is high or you cannot repay the balance before the rate increases, the transfer may not save as much money as expected.
Avoid using the newly available credit on your old card to make additional purchases. Doing so can leave you with debt on both cards.
Compare the total expected cost of the transfer with the cost of keeping your existing balance before making a decision.
9. Be Careful With Debt Consolidation Loans
A debt consolidation loan combines multiple debts into a new loan. It may simplify your payments and potentially reduce your interest costs if you qualify for favorable terms.
However, you should compare the complete cost before applying.
Check the new interest rate, origination fees, repayment period, monthly payment, and total amount payable. A lower monthly payment can sometimes mean that you will be paying for much longer.
Also consider whether the loan requires collateral. Securing a loan against your home or another important asset can introduce additional risks if you cannot make payments.
Consolidation does not automatically solve the underlying spending problem. If you transfer credit card balances to a loan but continue using the cards for purchases you cannot afford, your total debt may increase again.
Use consolidation only when the terms make sense for your situation and you have a realistic plan to avoid accumulating new balances.
10. Build a Small Emergency Fund
Paying off credit card debt is important, but using every dollar you have for repayment can leave you vulnerable to unexpected expenses.
If your car breaks down, you need urgent medical care, or your income temporarily decreases, you may have to use your credit card again if you have no money available.
A small emergency fund can help reduce this risk.
Start with an affordable target that could cover one common unexpected expense. You can build it gradually as your finances improve.
The right balance between emergency savings and debt repayment depends on your circumstances. If you have very high-interest debt, you may prefer to prioritize repayment after establishing a modest cash reserve and covering essential needs.
Avoid taking on additional debt just to build a large emergency fund quickly. Focus on a sustainable approach that helps you make progress without leaving yourself unable to pay essential bills.
11. Reduce Expenses to Free Up More Money
Small changes to your spending can create additional money for credit card repayment.
Start by reviewing your bank statements and identifying expenses you can reduce without compromising essential needs.
Review Subscriptions
Cancel unused subscriptions, memberships, or services that no longer provide enough value.
Plan Your Grocery Shopping
Make a shopping list, plan meals, compare prices, and use food you already have to reduce waste.
Compare Service Providers
Check whether you can reduce phone, internet, insurance, or utility costs without sacrificing necessary coverage or service quality.
Limit Impulse Purchases
Consider waiting 24 to 48 hours before making nonessential purchases. This gives you time to decide whether the item fits your budget.
Review Everyday Spending
Small purchases can add up over time. Track spending for a month to identify patterns rather than assuming that every expense is unnecessary.
You do not have to eliminate all entertainment or personal spending. A realistic budget is more likely to succeed than a plan that is too restrictive to maintain.
12. Increase Your Income if Possible
If most of your income already goes toward essential expenses, cutting costs may not create enough room to pay off your credit card balances quickly.
Depending on your circumstances, additional income may help.
You could consider freelance work, tutoring, part-time employment, overtime, or selling unused items. Choose opportunities that fit your skills, schedule, and local options.
Calculate any related costs before deciding whether an opportunity is worthwhile.
If you earn extra money, decide in advance how much can go toward your target credit card after accounting for essential expenses and urgent financial needs.
Even occasional additional payments can help reduce your balance, especially when directed toward a high-interest card.
13. Track Your Credit Card Debt Every Month
Monitoring your progress can help you identify problems early and stay motivated.
At the end of each month, review your credit card statements and record:
- Your starting balance.
- The amount you paid.
- Interest and fees charged.
- Any new purchases.
- Your ending balance.
- Your remaining debt target.
Example of a Monthly Tracking Table
| Month | Starting Balance | Payment | Ending Balance |
|---|---|---|---|
| Month 1 | $1,000 | $150 | $850 |
| Month 2 | $850 | $150 | $700 |
| Month 3 | $700 | $150 | $550 |
| Month 4 | $550 | $150 | $400 |
This example assumes there is no additional interest, fees, or new spending. Actual credit card balances may decrease more slowly because interest continues to accrue.
Check your statements rather than relying only on estimates. If your balance is not declining as expected, review your interest charges, payments, and recent purchases.
14. Avoid Common Credit Card Debt Mistakes
Certain habits can make it more difficult to manage credit card debt.
Making Only Minimum Payments Indefinitely
Minimum payments may keep your account current, but they can extend the repayment period and increase total interest costs.
Pay more when your budget allows.
Ignoring Statements
Reviewing statements helps you identify incorrect charges, unexpected fees, and changes to interest rates.
Check transactions regularly and report suspected unauthorized activity promptly.
Using One Credit Card to Pay Another Without a Plan
Cash advances and certain payment services may carry fees and high interest rates. Using one card to cover another can increase your total borrowing costs rather than solve the problem.
Understand the costs before attempting to move money between accounts.
Closing Cards Without Considering the Consequences
Closing a credit card may affect your available credit and, depending on your credit profile and scoring system, your credit score. It may still be appropriate in some situations, particularly if the card encourages overspending or has costly fees.
Consider the account terms, your spending habits, and your financial goals before deciding.
Ignoring Financial Hardship
If you are falling behind, contact the issuer rather than waiting for the problem to become more serious. Early communication may help you understand available arrangements.
Frequently Asked Questions
1. What is the best way to manage credit card debt?
Start by listing your balances, interest rates, and minimum payments. Create a budget, avoid unnecessary new borrowing, and choose a repayment strategy such as the debt avalanche or debt snowball method. Pay more than the minimum when you can afford to do so.
2. Should I pay off my highest-interest credit card first?
If your goal is to reduce interest costs, paying extra toward the highest-interest card is generally a good strategy, assuming other terms are comparable. Continue making required payments on your other accounts.
3. Is it better to pay the full credit card balance every month?
When possible, paying your statement balance in full by the due date can help you avoid interest on ordinary purchases if your card has a grace period and you meet its terms. Check your card agreement, especially if you have carried a balance or made cash advances.
4. What happens if I can only afford the minimum payment?
Your balance may take longer to repay, and you may pay more interest overall. Review your budget and consider paying extra when possible. If the minimum payment itself is unaffordable, contact your issuer to ask about hardship options.
5. Can a balance transfer help me pay off credit card debt?
It may help if the new card offers a lower overall borrowing cost and you can repay the transferred balance under the promotional terms. Compare fees, promotional periods, and the regular APR before applying.
6. Should I use my savings to pay off credit card debt?
It depends on your interest rates, emergency needs, and financial stability. Paying off expensive debt can reduce interest costs, but using all your savings may leave you without money for unexpected expenses. Consider maintaining a modest emergency reserve.
7. Does paying off credit card debt improve my credit score?
Reducing credit card balances can improve credit utilization, which may help your score under many credit-scoring models. However, the result depends on your credit history, reporting practices, and other factors. No particular score increase is guaranteed.
8. How long does it take to pay off credit card debt?
The timeline depends on your balance, interest rate, fees, and monthly payment. A debt repayment calculator can estimate how long repayment may take, but use your actual account terms and update your calculations as your balance changes.
Conclusion
Managing credit card debt effectively starts with understanding how much you owe and creating a repayment strategy that fits your budget. By limiting unnecessary new purchases, paying more than the minimum when possible, and choosing the right repayment method, you can gradually reduce your balances and limit interest costs.
Review your interest rates, contact your issuer if you are struggling, and carefully compare any balance transfer or consolidation offer before accepting it. At the same time, protect your ability to pay essential expenses and maintain a small emergency reserve when possible.
You do not have to eliminate your debt overnight. Consistent payments, realistic budgeting, and regular progress checks can help you regain control of your finances and work toward a more secure financial future.
Financial disclaimer: This article is for educational and informational purposes only and does not constitute personalized financial, legal, tax, or credit advice. Credit card interest rules, fees, balance transfer offers, credit reporting, and consumer protections vary by issuer and country. Review your card agreement and consider consulting a qualified financial professional or reputable credit counselor when appropriate.

Leave a Reply