
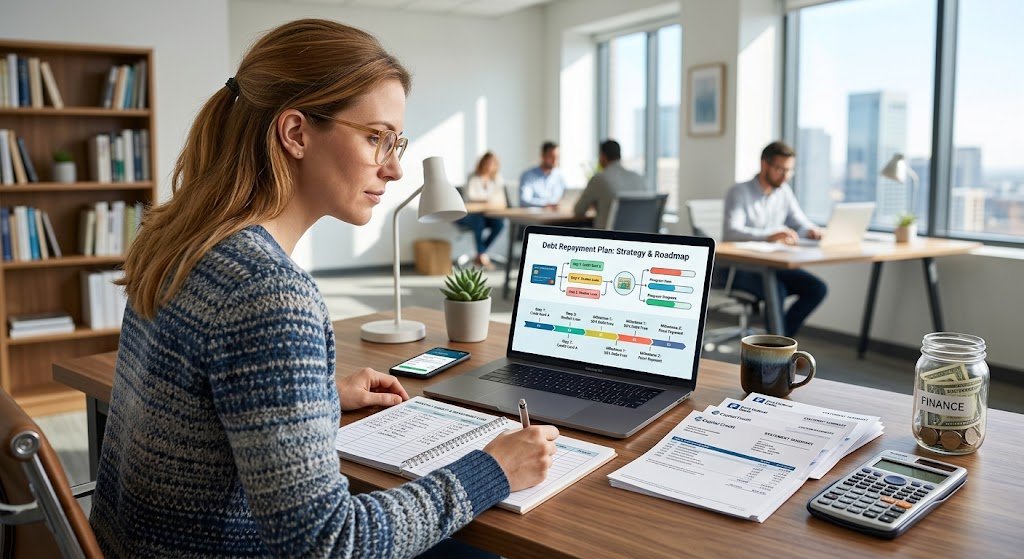
Debt can become stressful when you have several payments to manage, limited income, or unexpected expenses. Credit cards, personal loans, medical bills, and other financial obligations can make it difficult to save money and plan for the future. Without a clear strategy, you may continue making payments without feeling that your overall debt is decreasing.
- Creating a debt repayment plan can help you take control of your finances. It allows you to understand exactly how much you owe, organize your payments, choose which debts to pay first, and set realistic monthly targets.
- You do not need a high income or a large amount of savings to get started. The most important steps are understanding your financial situation, making a workable budget, and following a repayment strategy that fits your circumstances.
- In this guide, you will learn how to create a debt repayment plan step by step, compare popular repayment methods, avoid common mistakes, and track your progress until you become debt-free.
What Is a Debt Repayment Plan?
A debt repayment plan is a structured approach to paying off money you owe. It outlines your outstanding balances, minimum payments, interest rates, monthly repayment budget, and the order in which you intend to pay your debts.
- Instead of deciding which bill to pay each month without a clear strategy, you follow a plan designed around your income and financial priorities.
- A typical debt repayment plan includes:
- A complete list of your debts.
- The total amount you owe.
- The interest rate for each debt.
- The minimum monthly payment.
- Payment due dates.
- An affordable amount for additional payments.
- A target debt payoff date.
- A system for tracking your progress.
For example, if you owe money on two credit cards and one personal loan, your plan can help you determine which debt should receive extra payments while you continue meeting the required payments on the others.
A repayment plan does not eliminate debt immediately, but it gives you a practical way to reduce your balances over time.
Step 1: List All Your Outstanding Debts
The first step is to understand your complete debt situation. Gather recent statements, loan agreements, and account information so you can record accurate figures.
Do not focus only on the debts that worry you most. Include every relevant outstanding balance, even if the amount seems small.
For each debt, record the following information:
- Creditor or lender name.
- Current outstanding balance.
- Interest rate.
- Required minimum payment.
- Monthly due date.
- Any overdue amount or late fee.
- Special repayment conditions.
Example of a Debt Inventory
Suppose you have the following debts:
| Debt Type | Balance | Interest Rate | Minimum Payment |
|---|---|---|---|
| Credit card | $1,500 | 24% | $60 |
| Personal loan | $3,000 | 12% | $120 |
| Store credit | $500 | 18% | $30 |
| Total | $5,000 | — | $210 |
These figures are illustrative and do not represent a specific lender’s terms.
In this example, your total outstanding debt is $5,000, and your listed minimum monthly payments add up to $210.
Knowing these numbers helps you understand the size of your financial obligations and the minimum amount your budget needs to accommodate.
If you have overdue debts, variable interest rates, or accounts with serious consequences for nonpayment, record those details as well. They may affect the order in which you address your obligations.
Step 2: Calculate Your Monthly Income
Next, determine how much money you actually have available each month.
Use your take-home income rather than your salary before taxes or other payroll deductions. Include reliable sources of income, such as wages, regular freelance earnings, or other predictable payments.
If your income changes from month to month, use a conservative estimate based on your recent earnings. This helps prevent you from committing to payments you cannot afford during a slower month.
For example, your monthly income might include:
| Income Source | Monthly Amount |
|---|---|
| Main job | $1,800 |
| Part-time work | $200 |
| Total take-home income | $2,000 |
If the extra $200 from part-time work is not guaranteed, you may want to build your essential budget around the $1,800 and use additional earnings to accelerate debt repayment when they arrive.
Your repayment plan should reflect the money you can reasonably expect to receive, not an optimistic estimate that leaves you short of cash.
Step 3: Create a Realistic Monthly Budget
A budget helps you determine how much money you can safely use for debt repayment after covering your essential expenses.
Start by listing your monthly costs, including:
- Housing and rent.
- Groceries and household necessities.
- Electricity, water, gas, and other utilities.
- Transportation and fuel.
- Insurance and essential medical expenses.
- Phone and internet.
- Childcare or family responsibilities.
- Required debt payments.
- Irregular expenses that need to be funded over time.
Do not forget expenses that occur only a few times a year, such as vehicle maintenance, school fees, insurance renewals, or annual subscriptions. Setting aside a small amount each month for these costs can help prevent new debt.
Example Monthly Budget
Suppose your take-home income is $2,000 per month.
| Budget Category | Monthly Amount |
|---|---|
| Housing | $650 |
| Groceries | $300 |
| Utilities | $150 |
| Transportation | $150 |
| Phone and internet | $60 |
| Medical and personal essentials | $90 |
| Minimum debt payments | $210 |
| Irregular expenses reserve | $100 |
| Total planned expenses | $1,710 |
| Money remaining | $290 |
In this example, $290 remains after the listed expenses.
You might use some of that money for additional debt payments and keep some available for unexpected costs or a small emergency reserve.
The exact amount depends on your circumstances. If your budget is already tight, do not force yourself to make extra payments that prevent you from covering food, housing, utilities, or other essential needs.
Step 4: Choose a Debt Repayment Strategy
Once you know your income, expenses, and total debt, decide which balance should receive your extra payments first.
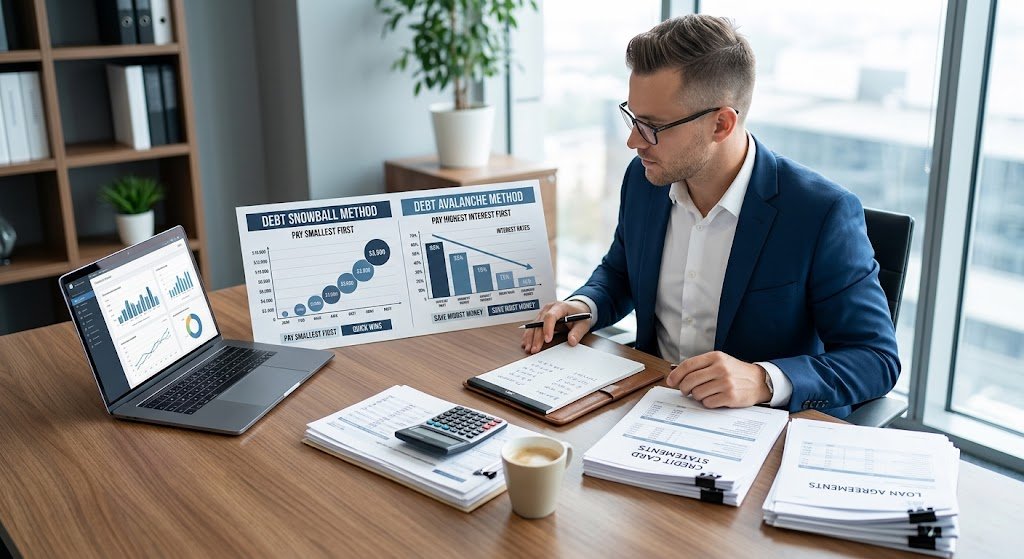
Two widely used approaches are the debt snowball method and the debt avalanche method.
Option 1: Debt Snowball Method
The debt snowball method prioritizes your smallest outstanding balance.
You continue making required minimum payments on your other debts and put any extra money toward the debt with the smallest balance.
After paying off that debt, you redirect the money you were paying toward it to the next-smallest debt.
- Example:
- Suppose you owe:
- $300 on a medical bill.
- $900 on a credit card.
- $2,000 on a personal loan.
Using the snowball method, you would target the $300 balance first, provided there are no urgent repayment conditions that require another debt to be addressed sooner.
The main advantage is motivation. Eliminating smaller balances can help you see progress early and reduce the number of debts you manage.
The drawback is that you may pay more interest if a larger balance has a much higher interest rate.
Option 2: Debt Avalanche Method
The debt avalanche method prioritizes the debt with the highest interest rate.
You make required minimum payments on your other debts and direct extra money toward the most expensive debt first.
After paying it off, you move to the debt with the next-highest interest rate.
Example:
- Suppose your debts are:
- $1,500 credit card at 24%.
- $500 store credit at 18%.
- $3,000 personal loan at 12%.
Using the avalanche method, you would generally target the credit card first because it has the highest interest rate.
This approach can reduce total interest costs when other repayment terms are comparable. However, your first payoff may take longer if the highest-interest debt has a large balance.
Which Repayment Method Should You Choose?
| Feature | Debt Snowball | Debt Avalanche |
|---|---|---|
| First priority | Smallest balance | Highest interest rate |
| Main benefit | Quick visible progress | Usually lower interest costs |
| Best for | People motivated by early wins | People focused on minimizing interest |
| Possible drawback | May cost more in interest | Early progress may feel slower |
Choose the method that fits your financial priorities and that you can realistically follow. You can also use a combination of the two, although paying a lower-interest debt first may increase your total interest costs.
Step 5: Decide How Much Extra You Can Pay
After accounting for essential expenses and required payments, decide how much additional money you can put toward your target debt.
Do not choose an amount simply because you want to become debt-free quickly. It must fit your actual budget.
For example, if your monthly income is $2,000 and your planned expenses leave $290, you might decide to allocate $190 toward additional debt repayment and retain $100 for extra flexibility.
Your total debt payment would then be $400 per month, consisting of $210 in minimum payments and $190 in extra payments.
These figures are only an example. Your available amount may be smaller, especially if your income is limited or your essential costs are high.
Start With a Manageable Amount
If you can afford only $25 or $50 in additional payments, start there.
A small, consistent extra payment can still help reduce your balance. If your income improves or you reduce certain expenses, you can increase the amount later.
It is better to follow a sustainable plan than to set an aggressive target that forces you to borrow again.
Step 6: Set Realistic Debt Payoff Dates
A target payoff date helps you understand how long your repayment plan may take.
The timeline depends on your outstanding balances, interest rates, fees, and monthly payments. Higher interest rates generally mean that more of your payments go toward interest rather than reducing the principal.
You can estimate your payoff timeline using a debt repayment calculator, your lender’s repayment information, or a budgeting spreadsheet.
Example of a Repayment Timeline
Imagine you owe $1,200 on a credit card and can pay $150 per month toward that debt.
Ignoring interest and fees, dividing $1,200 by $150 gives eight months.
However, if interest continues to accumulate, it will generally take longer than eight months unless your payments increase or other factors reduce the cost.
Use a realistic estimate rather than assuming your balance will decrease by the full amount of every payment.
Review your expected payoff date periodically and update it as your actual balance changes.
Step 7: Make Payments on Time
Payment consistency is an important part of any debt repayment plan.
Late payments may result in fees, additional interest, collection activity, or consequences for your credit history, depending on the debt and the rules in your country.
Consider setting reminders or using automatic payments for required minimum amounts if your account balance is sufficient and you can monitor the transactions.
If you use automatic payments, check that enough money is available in your account before each payment date. Otherwise, a failed payment may result in additional fees.
What If You Cannot Afford a Required Payment?
If your income drops or an unexpected expense makes a payment unaffordable, contact the creditor as soon as possible.
Ask whether the creditor offers hardship assistance, revised payment arrangements, temporary relief, or other options.
Get any revised agreement in writing and check whether it changes your interest rate, fees, repayment period, or credit reporting.
If you cannot pay all your bills, prioritize essential needs and consider seeking help from a reputable debt-advice service. Some obligations can have more serious consequences if unpaid than others.
Step 8: Reduce Expenses Where Practical
Reducing unnecessary spending can free up money for repayment. However, the goal is not to eliminate every enjoyable activity or compromise essential needs.
Look for changes that are realistic and sustainable.
Review Recurring Subscriptions
Check your bank statements for subscriptions and memberships you no longer use.
Canceling an unnecessary service may free up a small amount every month that can be redirected toward debt.
Plan Grocery Shopping
Prepare a weekly meal plan, make a shopping list, compare prices, and use ingredients you already have.
Reducing food waste and avoiding unplanned purchases can help you control costs without sacrificing essential nutrition.
Compare Service Plans
Review phone, internet, insurance, and utility costs. If suitable lower-cost options are available, compare their fees, coverage, and cancellation terms before switching.
Limit Unplanned Purchases
Consider waiting 24 to 48 hours before making nonessential purchases.
You can also set a reasonable personal spending allowance so that your budget remains realistic rather than overly restrictive.
Even if you can free up only a small amount, direct it toward your repayment target consistently.
Step 9: Look for Opportunities to Increase Your Income
If your essential expenses already consume most of your income, reducing spending may not create enough room to accelerate repayment.
In that case, increasing your income may help.Depending on your skills and circumstances, you could consider:
- Freelance writing, design, translation, or other services.
- Tutoring or teaching skills you already have.
- Part-time or weekend work.
- Selling unused household items.
- Taking additional shifts when available.
- Offering a service in your local community.
Before accepting extra work, account for transportation, equipment, supplies, taxes, and other related costs.
You do not have to earn a large additional amount for it to be useful. Even modest extra income can help reduce a balance when applied consistently.
If you receive a bonus, refund, or other one-time payment, consider using an affordable portion toward your target debt after accounting for essential needs and any urgent expenses.
Step 10: Build a Small Emergency Fund
An unexpected expense can interrupt your repayment plan and force you to borrow more money.
A small emergency reserve can help cover urgent expenses such as a necessary repair, medical cost, or temporary reduction in income.
You do not necessarily need to build a large emergency fund before paying extra toward debt. The right balance depends on your situation, including the interest rates you pay and how secure your income is.
Start with a manageable amount that could cover one common unexpected expense. Over time, you can work toward a larger reserve appropriate for your household.
If you already have overdue bills or debts with serious consequences for nonpayment, consider those risks when deciding how much money to keep available.
Step 11: Track Your Progress Every Month
Tracking your debt balances helps you see whether your plan is working.
At the end of each month, record:
- Your starting debt balance.
- The payments you made.
- Any interest or fees charged.
- Your new outstanding balance.
- The amount remaining to reach your target.
- Any changes to your income or budget.
A simple spreadsheet can be enough. You do not need expensive software to monitor your progress.
Example Debt Tracking Table
| Month | Starting Balance | Payment | Ending Balance |
|---|---|---|---|
| Month 1 | $1,000 | $150 | $850 |
| Month 2 | $850 | $150 | $700 |
| Month 3 | $700 | $150 | $550 |
| Month 4 | $550 | $150 | $400 |
This simplified example assumes no additional interest or fees. In a real account, the ending balance may be higher because interest and charges can affect the amount you owe.
Review the actual statements from your lenders to make sure your records are accurate.
Step 12: Adjust Your Plan When Life Changes
A debt repayment plan should be flexible enough to accommodate changes in your financial situation.
You may receive a pay increase, lose work hours, face an unexpected bill, or need to support a family member.
If your income increases, consider raising your extra debt payment while maintaining enough money for essential expenses and savings.
If your income decreases, revise your budget and contact creditors if you expect to miss required payments.
You can also reconsider your repayment method if your priorities change. For example, you might start with the snowball method to eliminate a small balance and later switch to the avalanche method to prioritize higher-interest debt.
The goal is steady progress, not perfection every month.
Common Mistakes to Avoid When Creating a Debt Repayment Plan
Even a well-designed plan can become difficult to follow if it includes unrealistic assumptions or overlooks important financial obligations.
1. Ignoring Your Full Debt Balance
Focusing on one account without listing your other debts can lead to missed payments and an inaccurate budget.
Record all your balances and review them regularly.
2. Setting Payments That Are Too High
If you commit too much money to debt repayment, you may not have enough left for food, housing, transportation, or unexpected costs.
Choose an amount that fits your actual budget.
3. Paying Extra Toward One Debt While Ignoring Others
The snowball and avalanche methods generally assume that you continue making required minimum payments on your other debts.
If you cannot afford those payments, contact your creditors and explore available options rather than simply ignoring the accounts.
4. Forgetting About Interest and Fees
Your balance may not decrease as quickly as expected when interest and fees accumulate.
Include these costs in your calculations and use realistic payoff estimates.
5. Taking on More High-Interest Debt
Continuing to borrow at high interest rates can undermine your repayment progress.
Avoid unnecessary borrowing and consider whether a small emergency reserve would help prevent future borrowing.
6. Giving Up After a Difficult Month
Unexpected expenses may force you to reduce a payment or revise your timeline.
That does not mean your plan has failed. Adjust the numbers and continue when you can.
Frequently Asked Questions
1. What is the first step in creating a debt repayment plan?
The first step is to list all your debts, including balances, interest rates, minimum payments, and due dates. This gives you a complete picture of what you owe and helps you choose a repayment strategy.
2. Should I pay off the smallest debt or the highest-interest debt first?
The debt snowball method prioritizes the smallest balance, while the debt avalanche method prioritizes the highest interest rate. The avalanche method generally reduces interest costs when other terms are comparable, while the snowball method may provide more immediate motivation.
3. How much money should I put toward debt each month?
Your monthly payment should depend on your take-home income, essential expenses, required payments, and financial circumstances. Start with an amount you can afford consistently and increase it when your budget allows.
4. Can I create a debt repayment plan with a low income?
Yes. Start by organizing your debts and building a realistic budget. Make required payments where possible, reduce avoidable expenses, and explore additional income opportunities if practical. If you cannot afford your payments, contact your creditors to discuss possible arrangements.
5. Should I save money while paying off debt?
A modest emergency reserve can help prevent unexpected expenses from forcing you to borrow again. The appropriate balance between savings and debt repayment depends on your essential needs, interest rates, and financial stability.
6. How long does it take to pay off debt?
The timeline depends on the amount you owe, interest rates, fees, and how much you can pay each month. A repayment calculator can help you estimate a target date, but review it regularly as your actual balances change.
7. Should I use a debt repayment calculator?
A calculator can help estimate how different payment amounts and interest rates affect your payoff date and total interest costs. Make sure the tool uses assumptions that reasonably match your lender’s terms, and treat its results as estimates.
8. What should I do if I cannot make my debt payments?
Contact your creditors as soon as possible and explain your situation. Ask about hardship programs, revised payment schedules, or other available options. If necessary, seek help from a reputable debt counselor or local consumer-advice organization.
Conclusion
Creating a debt repayment plan is an important step toward taking control of your finances. By listing your debts, calculating your income, building a realistic budget, and choosing a suitable repayment method, you can turn an overwhelming financial situation into a series of manageable steps.
Focus on making required payments where possible, directing extra money toward your chosen target, and avoiding unnecessary borrowing. Track your progress each month and adjust your plan when your circumstances change.
You do not have to pay off every debt at once or make large payments immediately. Consistency, realistic expectations, and careful financial decisions can help you reduce what you owe and move toward a more secure financial future.
Financial disclaimer: This article is for educational and informational purposes only and does not constitute personalized financial, legal, tax, or credit advice. Interest rates, debt collection rules, creditor options, and consumer protections vary by country and lender. Review your agreements and consider consulting a qualified financial professional or reputable debt-advice service when appropriate.

Leave a Reply